FCRA 2026: Foreign Money Must Have an Accountable Indian Trail
How the proposed law could strengthen transparency, asset accountability and the national interest
Total Views |


Foreign contributions can play a legitimate and valuable role in India. It can support healthcare, education, scientific research, disaster relief, social welfare and other public-benefit activities. But foreign funding also creates a legitimate public-policy question: when money enters India from abroad, who ultimately remains accountable for its receipt, utilisation and assets created from it?
The Foreign Contribution (Regulation) Amendment Bill, 2026 attempts to answer that question by strengthening the regulatory framework governing foreign-funded organisations.
The case for the Bill is particularly significant because of the scale involved. According to data cited in the parliamentary analysis, 13,520 organisations received ₹55,741 crore in foreign contribution between 2019 and 2022. As of 15 July 2026, the FCRA portal showed 14,449 active certificates, 22,498 cancelled certificates and 15,212 deemed expired certificates.These numbers demonstrate the size of the regulatory system.
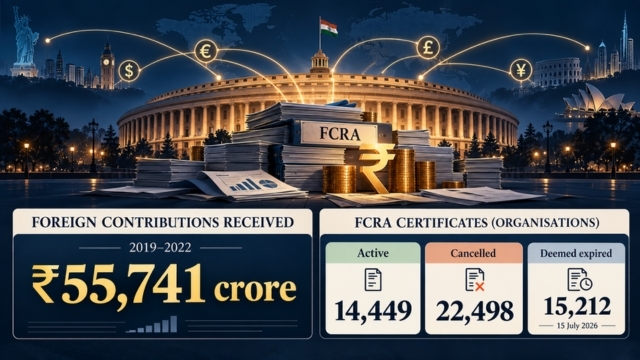
However, one distinction is essential: cancelled or expired certificates cannot automatically be described as violations. They may reflect several statutory circumstances, including non-renewal, surrender, inactivity or violations. A responsible analysis must therefore distinguish between registration status and proven violations.
The missing link: What happens to foreign-funded assets?
The strongest argument for the 2026 Bill lies in its attempt to close an accountability gap. The Bill proposes a ‘Designated Authority’ to supervise, manage and dispose of foreign contribution and assets when an organisation's FCRA certificate is cancelled, surrendered or ceases because renewal is not obtained or is denied.
Consider a simple example – Suppose an organisation receives foreign contributions and uses part of it to establish a hospital, school, training centre or community facility. Years later, its FCRA certificate ceases. The organisation may continue functioning with domestic resources.
The important question then becomes: What happens to the asset created, wholly or partly, from foreign contribution?
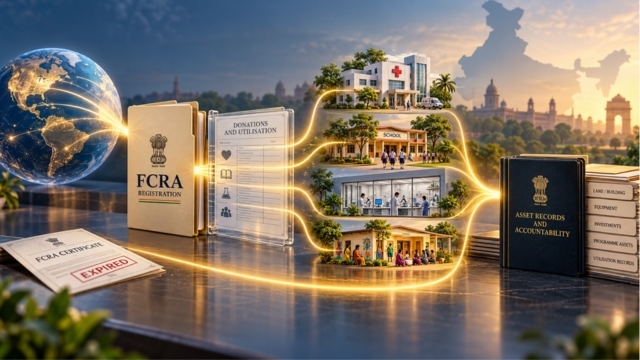
The Bill provides a legal mechanism for addressing precisely this situation. Foreign-funded assets would initially vest provisionally in the Designated Authority. If the organisation restores or obtains the required FCRA status within the prescribed framework, the relevant assets or unutilised contribution can be returned. If the required conditions are not fulfilled, the vesting can become permanent.
This creates a clearer accountability chain: Foreign source → Indian organization → approved purpose → expenditure → asset → continuing accountability. That is a significant regulatory principle.
₹55,741 crore: why the scale matters
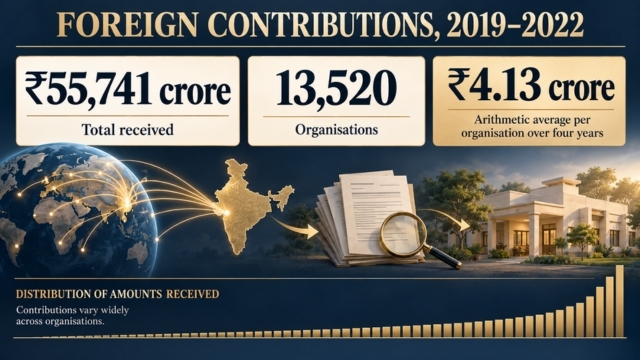
Between 2019 and 2022, 13,520 organizations received ₹55,741 crore in foreign contributions. This works out to an arithmetic average of about ₹4.13 crore per organisation over four years. This average does not mean that each organisation received ₹4.13 crore. Foreign contribution is unevenly distributed, with some organisations receiving substantially more and many receiving considerably less.
Nevertheless, the figure demonstrates why the Government requires a reliable system for tracing foreign money.
The question is not whether foreign philanthropy is good or bad.
The better question is: Was the money received legally, used for the declared purpose, properly accounted for and converted into legitimate public benefit? The FCRA framework should be capable of answering all four questions.
From money monitoring to asset monitoring
Earlier regulatory systems naturally concentrated on the receipt and utilisation of foreign contribution. The 2026 Bill goes further by addressing assets created from that contribution. This is important because money can eventually become a permanent physical asset. ₹10 crore received as foreign contribution may no longer exist as cash after several years. It may have become a building, laboratory, hospital equipment, educational infrastructure or another capital asset. Therefore, monitoring only the bank transaction is insufficient.
A modern regulatory system must be able to follow the trail: Money → utilisation → project → asset → ownership/control → continuing accountability. The Bill attempts to provide this missing final link.
Public purpose instead of private benefit
The Bill provides that permanently vested assets may be used for public purposes. The Designated Authority may transfer them to government ministries, departments or agencies, or dispose of them through prescribed processes. Proceeds from disposal and unutilised foreign contribution are proposed to be credited to the Consolidated Fund of India.
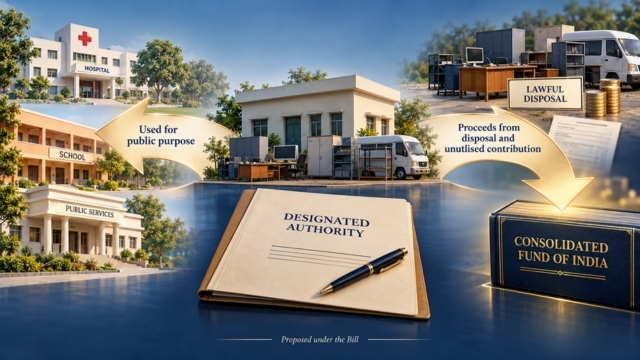
From a public-finance perspective, this is significant. If an asset has been created substantially through regulated foreign contribution and the organization permanently leaves the FCRA framework, the law should not permit the asset to fall into an undefined regulatory vacuum. A transparent statutory destination is preferable to uncertainty.
₹10 lakh activity benchmark: ending dormant compliance
The FCRA Amendment Rules, 2026, notified on 22 June 2026, introduced a measurable benchmark for assessing “reasonable activity”. An organization is deemed to have undertaken reasonable activity in its chosen field if it has utilised at least ₹10 lakh of foreign contribution during the preceding two financial years. This can be viewed as an attempt to distinguish an organisation that is genuinely carrying out approved activities from one that merely maintains a registration without meaningful foreign-funded activity. The principle is simple: Registration should correspond with genuine activity, compliance and accountability. At the same time, the ₹10-lakh benchmark deserves careful implementation so that legitimate small organizations are not unintentionally disadvantaged merely because their activities are low-cost.
Greater responsibility for key functionaries
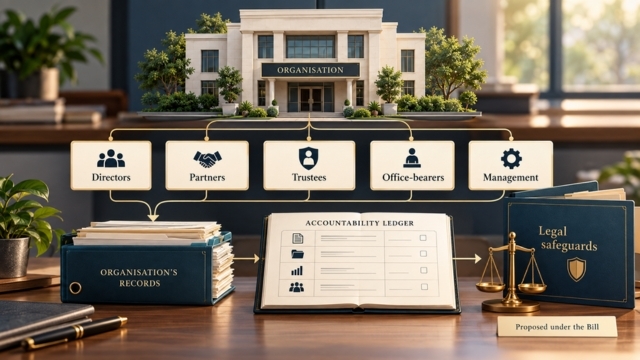
The Bill also defines “key functionaries” more explicitly, covering directors, partners, trustees, office-bearers and persons responsible for management. This is important because organizational responsibility should not stop at an institutional name. If an organisation violates the law, the regulatory framework should be capable of identifying the persons responsible for its management while retaining appropriate legal safeguards. This can strengthen corporate and institutional accountability.
The Bill is not simply a harsher punishment law
An interesting aspect is often missed in public debate. The existing framework provides for imprisonment of up to five years for contravention. The 2026 Bill proposes reducing the maximum imprisonment to one year. It also proposes prior approval of the Central Government before an investigation for an offence under the Act is initiated. Therefore, it would be inaccurate to describe the Bill merely as an attempt to increase criminal punishment. Its principal direction is broader: greater administrative control, clearer asset accountability, stronger compliance and better traceability of foreign contribution.
Places of worship receive specific protection
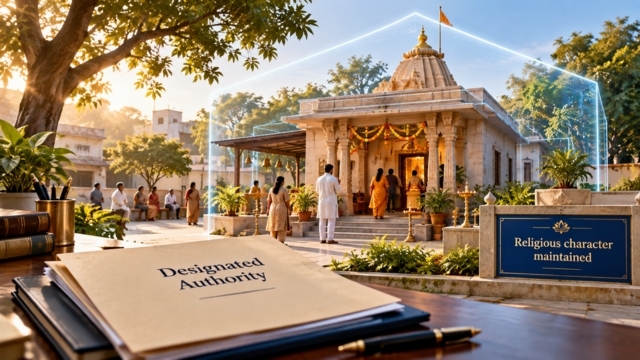
The Bill also contains an important safeguard for places of worship.
Where a permanently vested asset is wholly or partly a place of worship, the Designated Authority is required to ensure that its religious character is maintained. This indicates that regulatory control over an asset does not necessarily mean that its social or religious function must disappear.
India is not alone in regulating foreign funding
Foreign-funding transparency is not unique to India. Governments across democracies have developed mechanisms for recording, monitoring or disclosing foreign funding and foreign influence. The broader principle is therefore not controversial in itself: foreign funding can be permitted while remaining subject to transparency and accountability. The Ministry of Home Affairs itself describes FCRA regulation as intended to ensure that foreign contribution is not used for activities detrimental to national interest.
A necessary safeguard: accountability must include due process
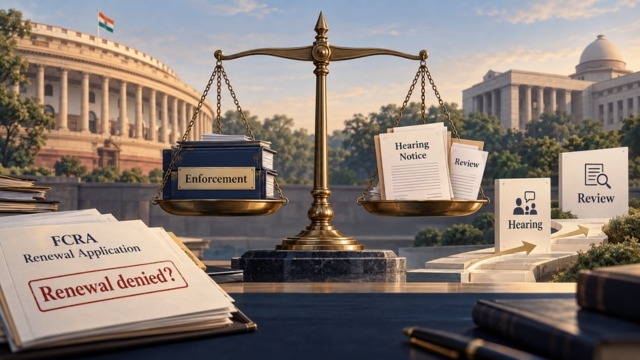
Supporting the Bill does not mean that every provision should be beyond parliamentary scrutiny. One legitimate issue identified in the parliamentary analysis concerns the absence of a specific appeal mechanism where renewal is denied. Since non-renewal could result in asset vesting, an appropriate hearing and review mechanism would strengthen the law. This is not an argument against regulation. Rather, it is an argument for better regulation. The final law should achieve both objectives: strong enforcement + fair procedure. That balance would make the legislation more durable and credible.
Why Parliament should take the Bill seriously
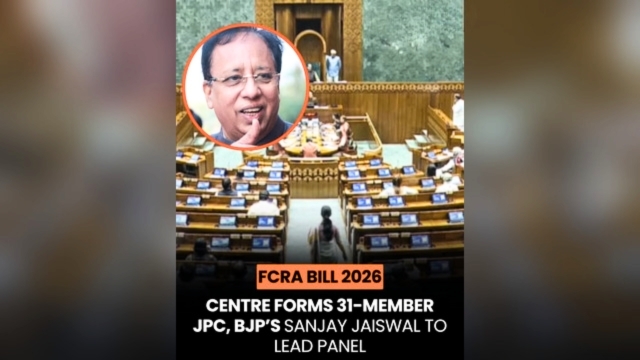
The Bill was introduced in the Lok Sabha on 25 March 2026. Both Houses subsequently approved its reference to a Joint Parliamentary Committee for detailed scrutiny. In September 2026, a 31-member JPC was constituted, with BJP MP Sanjay Jaiswal as chairperson.
This parliamentary process is valuable because the Bill affects several interconnected areas - foreign funding, financial transparency, national security, charitable and social-sector activity, institutional accountability;, ownership and management of foreign-funded assets and public interest. A detailed parliamentary examination can improve the Bill without weakening its central objective.
The real test: follow the money
The debate should ultimately move beyond slogans. The most useful test is a data-based one: Where did the foreign money come from? Who received it? How much was received? What was the declared purpose? How much was actually utilised? Where was it utilised? What assets were created? Who controls those assets today? If the regulatory system can answer these questions transparently, it strengthens public confidence.
Foreign contribution should come with Indian accountability
India does not need to reject legitimate foreign contributions. Nor should genuine humanitarian, educational, scientific or social organisations be discouraged. But foreign contribution enters India under a legal permission framework. Therefore, the responsibility attached to that money should not disappear when the organisation's FCRA certificate ends.
The 2026 Bill attempts to establish precisely this principle. Its proposed Designated Authority, provisional and permanent vesting mechanism, public-purpose utilisation of assets, responsibility of key functionaries and stronger compliance architecture can make the FCRA system more transparent and accountable.
The figures themselves explain why this matters: ₹55,741 crore received by 13,520 organisations between 2019 and 2022, alongside thousands of active, cancelled and expired FCRA certificates. The objective should therefore be neither blanket suspicion of civil society nor unrestricted foreign funding.
There should be transparent foreign funding under Indian law. The principle is simple: Foreign money may enter India for legitimate purposes, but its legal trail, utilisation and assets created from it must remain accountable to India.
Written by
Dr. Lavakush Singh
Financial Analyst | Academic & Researcher